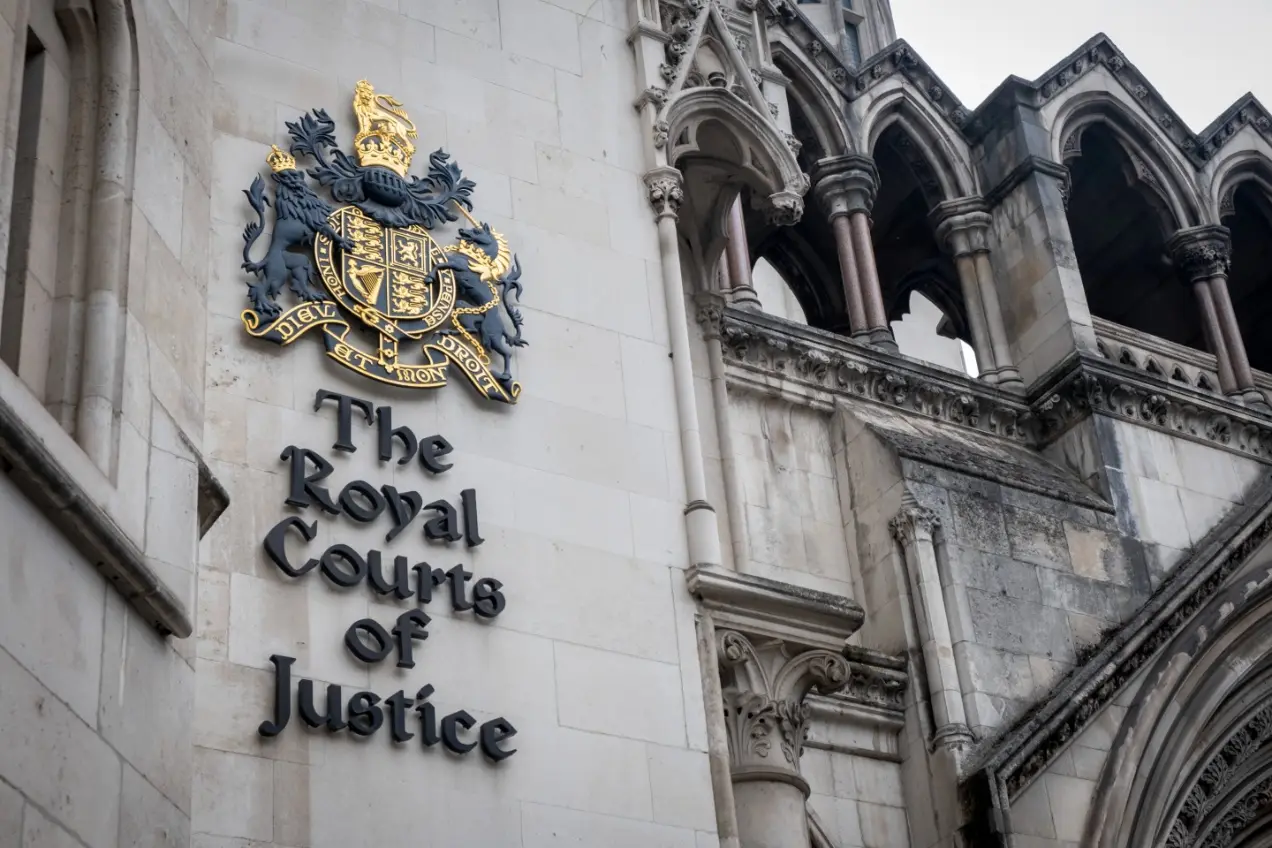
On the 22nd of October 2026, the English Court of Appeal confronted a unique question of investment arbitration, when faced with the Republic of India v Ras Al Khaimah Investment Authority case, in which it dismissed India’s appeal against a finding of arbitral jurisdiction. A government can leave a foreign investor’s share untouched while undermining the business that gives them value. The question therefore is:
Does that mean its actions affect the investment only indirectly?
The dispute arose from RAKIA’s investment in ANRAK Aluminium, an Indian company established to develop an aluminium project in Andhra Pradesh. The project depended on a bauxite supply agreement with a State-owned corporation. Governmental actions leading to that agreement’s cancellation prompted RAKIA to bring arbitration under the 2013 India-UAE bilateral investment treaty. RAKIA alleged breaches of investment protections. India then disputed both liability and jurisdiction.
The jurisdictional difficulty lay in the relationship between two treaty provisions. Article 10.2 addresses measures taken by India’s central or state governments when exercising executive powers. Article 1.8 defines a measure as binding governmental action “applied directly to an Investment”. Article 1.1, however, expressly includes shares within the definition of investment. Recognising shares as protected assets therefore implies another question:
What must governmental action do to qualify as directly applied to them?
The tribunal answered this question by distinguishing the company from its shareholder. In its 2022 award, it assumed that the relevant acts caused loss to ANRAK and consequently diminished the value of RAKIA’s shares. Nevertheless, those acts applied directly to the companies involved, with only an indirect effect on RAKIA’s investment. It therefore declined jurisdiction. RAKIA challenged that conclusion under section 67 of the Arbitration Act 1996.
The High Court rejected the tribunal’s approach in June 2025. Its reasoning distinguished ownership of an asset from the character of that asset as an investment. A shareholder does not need to own the company’s refinery for governmental action against the underlying undertaking to apply directly to its investment. The court considered both directness and application satisfied in the circumstances.
The Court of Appeal agreed with the central distinction. RAKIA’s investment remained its shareholding, and ANRAK’s assets did not become RAKIA’s assets. However, the shares had to be understood as representing capital invested in the undertaking. Ending its primary bauxite supply could therefore apply directly to that investment even without altering the shareholder’s legal rights.
This reading is supported by the text of the treaty beyond the express inclusion of shares. Article 1.1 preserves an investment’s character when its form changes, while Article 3.2 encourages investors to establish legal entities for investment projects. Article 7.3 also contemplates compensation for foreign shareholders when a State expropriates a locally incorporated company’s assets. Read together, these provisions make corporate intermediation part of the treaty’s protective framework.
Directness nevertheless remains a limit. The appellate court rejected a simple distinction between targeted action and general regulation: an industry-wide rule could apply directly to investments. Conversely, consequences for separate businesses servicing the project could be indirect. The boundary depends on the relationship between the action and the investment, rather than the measure’s breadth alone.
The judgement thus sharpens the question that treaty drafters and tribunals must answer. Yet, the judgment leaves the threshold of directness uncertain. Rejecting interference with shareholder rights as a necessary condition does not explain precisely when economic consequences become direct application. The Court of Appeal thus resolves the jurisdictional dispute, without establishing a comprehensive test for future cases.
When shares receive protection, how far does that protection reach into the business they finance? Corporate separateness identifies what the investor owns, but cannot alone resolve the scope of treaty protection. RAKIA has secured access to a merits determination, but whether India breached its obligations remains to be decided.
References:
Agreement between the Government of the Republic of India and the Government of the United Arab Emirates on the promotion and protection of investments, December 12, 2013.
Arbitration Act 1996, c. 23(UK).
Arato, J., Claussen, K., Lee, J., & Zarra, G. (2019). Reforming shareholder claims in ISDS (Academic Forum on ISDS Concept Paper No. 2019/9, Version 2). Academic Forum on ISDS.
Bentolila, D. (2010). Shareholders’ action to claim for indirect damages in ICSID arbitration. Trade, Law and Development, 2(1), 87–144.
Bottini, G. (2008). Indirect claims under the ICSID Convention. University of Pennsylvania Journal of International Law, 29(3), 563–639.
Gaukrodger, D. (2013). Investment treaties as corporate law: Shareholder claims and issues of consistency (OECD Working Papers on International Investment No. 2013/03). OECD Publishing. https://doi.org/10.1787/5k3w9t44mt0v-en
Gaukrodger, D. (2014). Investment treaties and shareholder claims for reflective loss: Insights from advanced systems of corporate law (OECD Working Papers on International Investment No. 2014/02). OECD Publishing. https://doi.org/10.1787/5jz0xvgngmr3-en
Ras Al Khaimah Investment Authority v. Republic of India, [2025] EWHC 1553 (Comm) (High Court of Justice of England and Wales, June 20, 2025). https://caselaw.nationalarchives.gov.uk/ewhc/comm/2025/1553
Republic of India v. Ras Al Khaimah Investment Authority, [2026] EWCA Civ 1358 (Court of Appeal of England and Wales, October 22, 2026). https://caselaw.nationalarchives.gov.uk/ewca/civ/2026/1358